Ian Cheng — September 15, 2026
In his first month back in office, President Donald Trump announced that the US was abandoning a global agreement that would have adopted a 15% global corporate minimum tax, likely causing many companies to breathe a sigh of relief. Subsequently, in 2025, 40 major American companies saved an estimated $11 billion by shifting profits to tax havens, or countries that offer very low or zero tax rates. However, the IRS’ pursuit of Corporate America’s overseas profits is not over.
The IRS, or the Internal Revenue Service, handles all things tax-related in America, such as collecting taxes, helping people navigate the system, and enforcing federal laws. Its pursuit of overseas profits intensified during the Obama administration. For example, in April 2016, the Treasury Department announced several regulations aiming to discourage inversions: where US companies buy foreign firms and then move their headquarters overseas. This directly caused American pharmaceutical giant Pfizer to call off its planned purchase of Allergan, which is based in Ireland. Specifically, the deal would have moved Pfizer’s executive offices to Ireland, decreasing their tax rate from 25% to about 17-18% within a year.
Yet, moves to maximize profits through going international have not stopped. Currently, the mechanism in the spotlight is transfer pricing, a practice that sets prices for internal transactions between a parent company and its foreign subsidiaries. While completely legal, it can be manipulated to allocate earnings across subsidiaries, in turn potentially reducing tax burden.
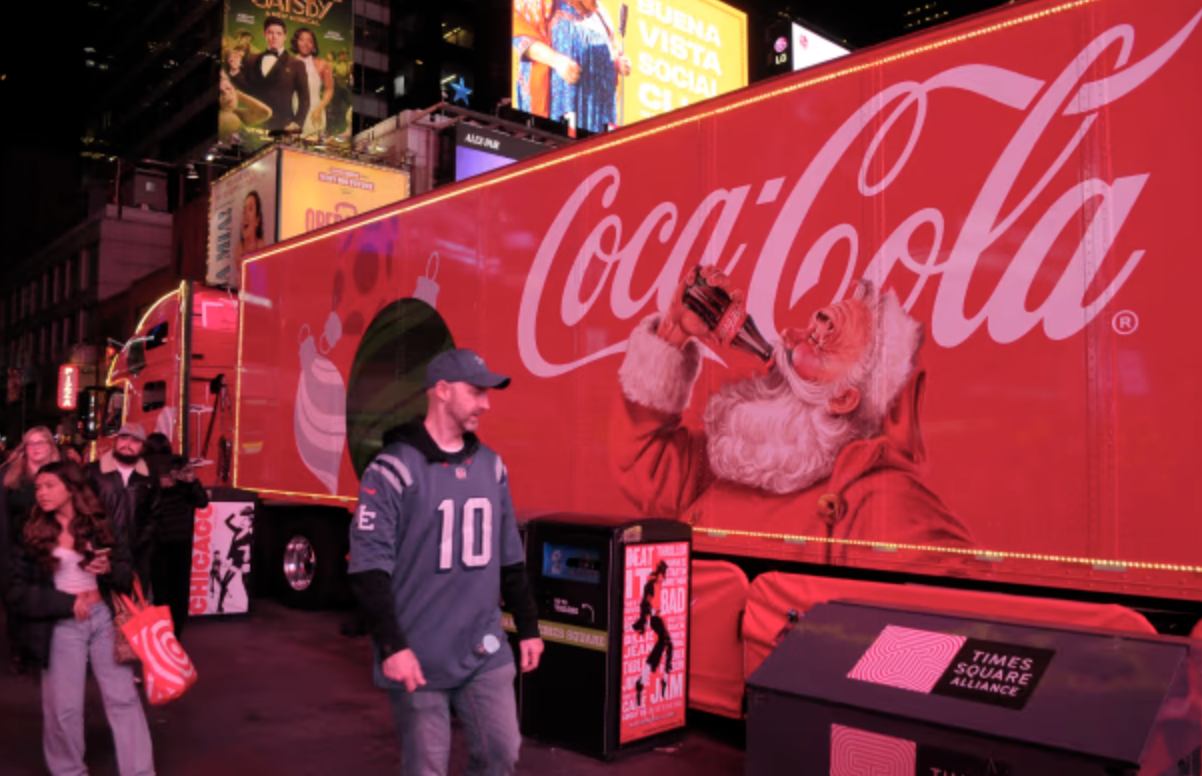
For instance, Coca-Cola and the IRS are in a dispute over profits from the 2007-2009 tax years. In 1996, the drinkmaker and the IRS settled on a “10-50-50” formula, where foreign subsidiaries like those in Ireland, Brazil, Chile, and Costa Rica earned a 10% margin on sales to local bottlers. The rest of the money was split 50-50 between the parent company in the US and the foreign subsidiaries. Consequently, these foreign subsidiaries were allocated over half of their relevant total international profits, meaning the profits were subject to lower corporate tax rates.
Coca-Cola defended their continued usage of the formula, while the IRS argued that since the US parent company owned the key intellectual property, namely trademarks, brand names, and secret formulas for the drink, the US parent company deserved more of the profits and 10-50-50 was not valid.
The IRS then presented evidence that subsidiaries were earning disproportionately high returns (ex. Coca-Cola Ireland earned a 215% return on operating assets compared to a 53% return for the parent company). This contributed to the US Tax Court’s 2020 ruling that Coca-Cola’s continued use of 10-50-50 decades after the 1996 settlement was unjustified. The court ordered the reallocation of $9 billion in foreign profit from subsidiaries back to the Coca-Cola parent company in the US, resulting in an additional $2.7 billion in taxes. Critically, this indicated that using transfer pricing to evade taxes isn’t necessarily legal, even if it’s based on prior agreement.
However, the drinkmaker has appealed the decision. It is uncertain that the IRS will come out completely victorious. In a hearing on June 25th, Attorney Gregory Garre compared the IRS’ retroactive decision to disallow 10-50-50 to “encouraging someone to cross the street, then issuing them a billion-dollar ticket for jaywalking.” Judge Barbara Lagoa expressed that “this concept of retroactivity seems to me a bit of a due process violation.” Additionally, judges were reportedly sympathetic to Coca-Cola’s arguments and pressed the IRS over its pursuit of the company.
The litigation is complex, even involving the issue of “blocked income,” where foreign laws like those in Brazil limit the amount of profit that can be sent from a subsidiary to its US parent company. Even so, the implications are huge: since Coca-Cola has continued to use 10-50-50 through 2025, it could be taxed a grand total of $20 billion. Fellow corporations with similar disputes against the IRS like Amgen, Meta, and Airbnb will be on the watch. The verdict could either give them a strong legal framework to protect profit-allocation to their foreign subsidiaries (if Coca-Cola wins), or further embolden the IRS to challenge their profit-allocation arrangements.
Read more here: